
PM Vidyalaxmi Education Loan: Eligibility and Interest Support
Explore collateral-free education loans for eligible QHEI students and the separate criteria for 3% interest subvention.
Eligibility: Students admitted on merit to an eligible Quality Higher Education Institution (QHEI), subject to scheme rules.
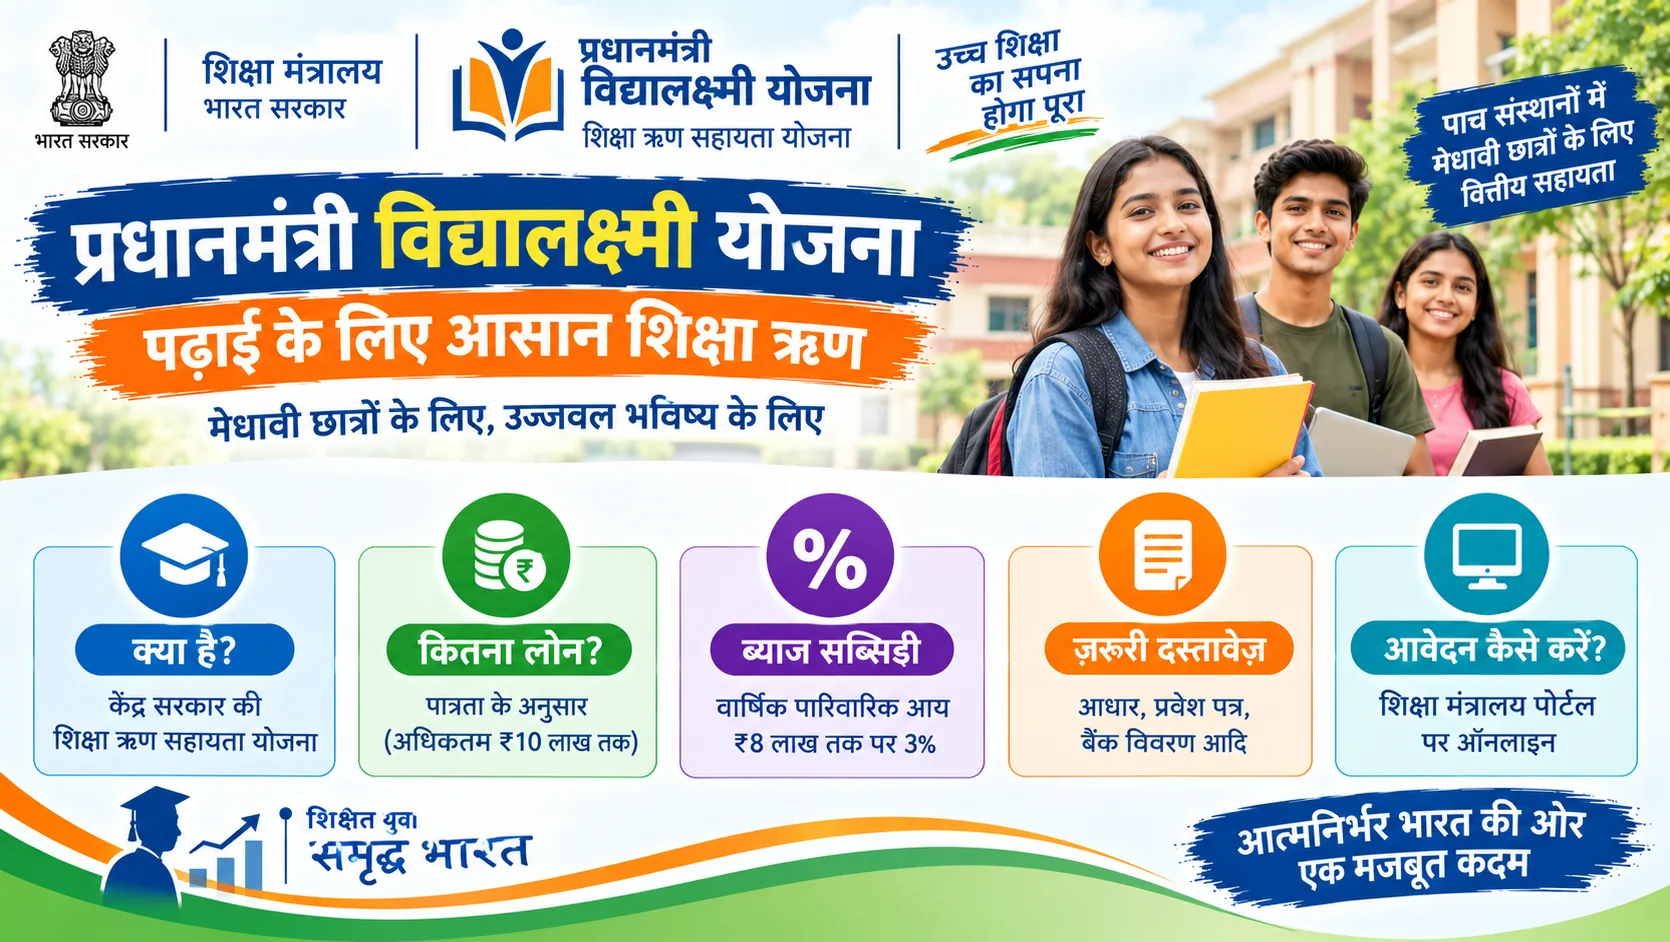
What PM Vidyalaxmi is
PM Vidyalaxmi is a Central Sector education-loan support programme approved in November 2024. It is intended to help students who receive merit-based admission to eligible Quality Higher Education Institutions (QHEIs). The scheme is not a general cash scholarship and does not mean that every college student receives a free ₹10 lakh payment. Financial support flows through a bank education loan, while the interest-subsidy benefit has separate conditions and limits.
Checking eligible institutions
The student must hold qualifying merit-based admission to an institution covered under the officially recognised QHEI framework. Institution eligibility can depend on the correct university, constituent-college relationship and AISHE or other institutional identifiers. Ministry clarifications in 2026 addressed some constituent-college situations. Do not rely on an outdated third-party college list or assume that every institution carrying the word “university” is covered. Verify the current government QHEI list before proceeding with a loan application.
Collateral-free loans versus interest support
The specialised loan product provides collateral-free and guarantor-free education financing for eligible admitted students, subject to standard verification and bank processes. The actual sanctioned amount depends on educational expenses and credit assessment; there is no unconditional guaranteed ₹10 lakh disbursement for each applicant. A distinct benefit provides 3% interest subvention on loans up to ₹10 lakh for students whose annual family income is up to ₹8 lakh, provided the remaining conditions are met. Official guidance also limits the number of fresh interest-subsidy beneficiaries each year.
What the ₹8 lakh income condition means
The ₹8 lakh annual family-income threshold is particularly important for the 3% interest-subvention component. It should not be incorrectly presented as a blanket limit on the basic collateral-free education-loan product. Some students from lower-income groups may fall under other interest support programmes, whose interaction and restrictions should be checked under current guidance. Ask the bank to identify the exact support programme it is assessing rather than making assumptions based on an advertisement.
What documents are useful
Keep admission evidence, course and fee structure, educational certificates, identity proof, student details, income documentation where needed and bank-requested financial information accessible. The final document list depends on the lender and the student’s situation, and some institutions may require an additional confirmation. Reconcile spelling and ID details before uploading. Do not send financial records to unofficial intermediaries or pay anyone promising an automatic approval.
Application walkthrough
First read the Ministry of Education guidelines and check the institution on the eligible QHEI list. Use the authorised education-loan portal linked by the official scheme resources to register and complete student, course, institution and cost details. Upload supporting documents, select available lending options as provided, and retain your application reference. The lender may contact the institution or applicant for checks. The bank ultimately decides sanction and terms, while subsidy eligibility is independently assessed.
Before accepting an offer
Check the interest rate, moratorium, repayment schedule, fees, insurance, eligible expenses and how any interest subvention is calculated or credited. Collateral-free does not mean interest-free. A 3% subvention does not automatically erase all interest obligations. Also confirm how the bank handles course changes, withdrawals or missing paperwork. Current availability, bank procedures and QHEI eligibility can change; always rely on the latest official notice and written loan terms.
Frequently asked questions
Q: Is PM Vidyalaxmi a scholarship?
A: It principally supports education loans, with separate interest subvention.
Q: Does every student qualify for 3% relief?
A: No; the income test and other programme conditions apply.
Q: Is every college eligible?
A: No; the institution must qualify as a QHEI.
Q: Is a bank loan guaranteed?
A: No; the lender conducts checks before sanction.
Explore related government schemes
Always check the official website for final and accurate information.
Visit official website: www.education.gov.in ↗Last updated: 18 Oct 2026