
PM Shram Yogi Maandhan: ₹3,000 Pension Eligibility and Contributions
Guide for eligible unorganised workers on PM-SYM pension after age 60, contribution amounts, exclusions and CSC enrolment.
Eligibility: Unorganised workers aged 18–40 earning ₹15,000 or less monthly, subject to EPFO/ESIC/NPS and taxpayer exclusions.
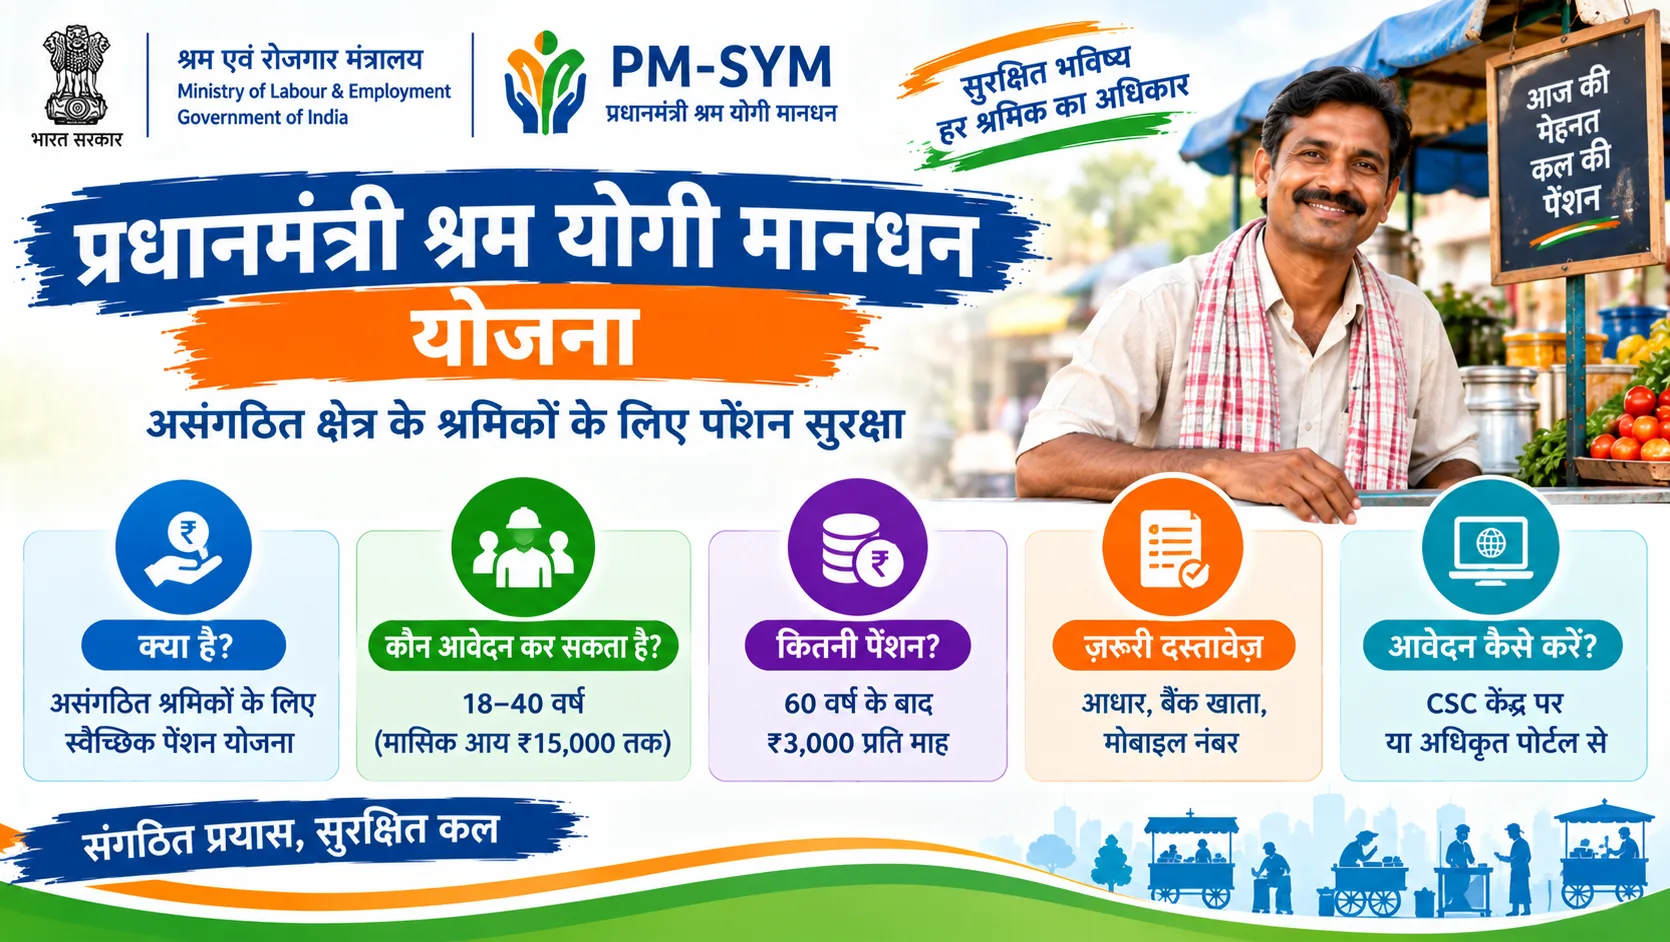
What PM-SYM provides
Pradhan Mantri Shram Yogi Maandhan, usually abbreviated PM-SYM, is a voluntary contributory pension programme for eligible low-income workers in India’s unorganised sector. It is intended to support old-age income security. Rather than paying an immediate benefit to all new applicants, it requires eligible subscribers to contribute regularly while they work. The central government contributes a matching amount under the programme. Subject to the scheme conditions, subscribers receive an assured ₹3,000 monthly pension after reaching age 60.
Who can enrol
The normal entry age is 18 to 40 years. A worker’s monthly income must be ₹15,000 or below. The scheme addresses people working outside regular organised employment, potentially including occupations such as domestic work, street vending, construction and small self-employed trades. Formal eligibility exclusions matter: an EPFO or ESIC member, certain National Pension System members covered by the relevant rules, and income-tax assessees are not eligible. Work status, income and relevant membership should be checked before applying.
Contribution amount and example
The beneficiary contribution depends on the age when the person joins. The official contribution table shows a range of ₹55 to ₹200 per month for different entry ages. The Government of India contributes an equal matching amount. For illustration, a subscriber entering at age 29 contributes ₹100 a month while the government adds ₹100. Someone joining later may pay more each month than a younger entrant. These are pension contributions, not instalments of a loan and not an investment that promises immediate withdrawal.
What happens at age 60
The stated benefit is an assured pension of ₹3,000 each month after the subscriber reaches 60, subject to the programme’s continuing conditions. It is important to distinguish the age at enrolment from the age when pension becomes payable. If a worker has missed contributions, changed banks or otherwise stopped participating, do not assume the full pension will remain automatically payable. Review the official rules and any current guidance concerning defaults, exit and family benefits.
Difference from Atal Pension Yojana
PM-SYM and Atal Pension Yojana are distinct programmes. PM-SYM is specifically designed for qualifying unorganised workers under the prescribed monthly-income limit and has an assured ₹3,000 pension provision. Atal Pension Yojana has a different contribution and eligibility framework. Readers already participating in another pension arrangement should not assume that they can join both without considering exclusions. Clarify any membership or overlap question with an authorised CSC or the administering department.
Documents and bank readiness
The labour ministry’s scheme document identifies an Aadhaar number, a mobile phone and savings-bank or Jan Dhan account details as essential for enrolment. A bank passbook is useful when visiting a CSC. Check spellings, account numbers and birth dates carefully. Keep receipts or enrolment records for later support requests. Never disclose internet-banking credentials, OTPs or PINs to a person who claims to guarantee acceptance.
Steps to enrol
Visit a nearby Common Service Centre and check that PM-SYM enrolment is currently being facilitated. Supply the required identification and bank information along with applicable self-declarations. Review the age-based contribution displayed by the operator before proceeding, and ask for a receipt and the subscription reference. Continue monitoring contributions and update details through official support channels if they change. Read the scheme terms for exits, contributions and benefits instead of relying on a verbal promise.
Frequently asked questions
Q: Can someone aged 45 join?
A: The stated entry age is 18–40, so a new 45-year-old applicant would not normally qualify.
Q: Is the government contribution equal to the worker contribution?
A: Yes, under the programme.
Q: Is the monthly ₹3,000 paid immediately?
A: No, the pension becomes relevant after age 60.
Q: Is this a loan?
A: No, it is a contributory pension scheme.
Explore related government schemes
Always check the official website for final and accurate information.
Visit official website: labour.gov.in ↗Last updated: 20 Oct 2026