
Pradhan Mantri Mudra Yojana (PMMY)
PM Mudra Yojana offers collateral-free business loans of up to ₹20 lakh to eligible micro-enterprises.
Eligibility: Eligible micro-business borrowers; Tarun Plus requires successful repayment of a previous Tarun loan.
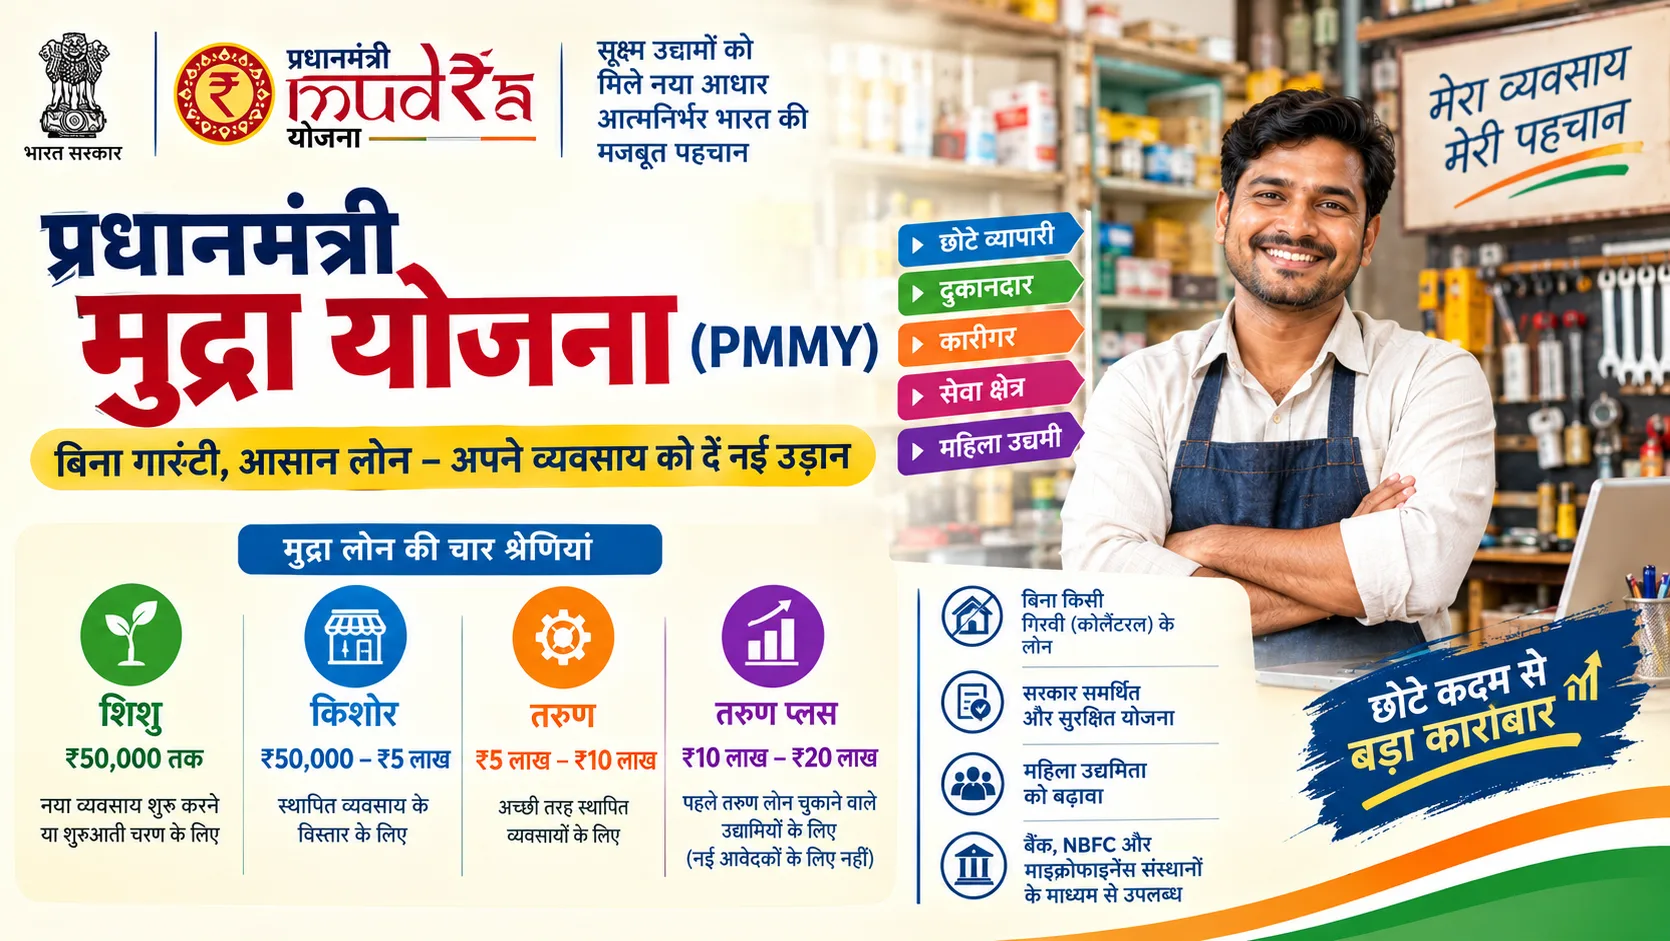
What Is Pradhan Mantri Mudra Yojana (PMMY)?
Pradhan Mantri Mudra Yojana (PMMY) is a Government of India initiative that helps eligible micro-enterprises access business loans from formal financial institutions. Launched on 8 April 2015, the scheme supports income-generating activities in manufacturing, trading, services and certain activities allied to agriculture.
PMMY loans are provided through participating banks, Non-Banking Financial Companies (NBFCs), Micro Finance Institutions (MFIs) and other eligible lenders. The funds may be used for business requirements such as equipment, inventory, expansion and working capital.
The maximum Mudra loan limit is now ₹20 lakh. However, the amount above ₹10 lakh is available under the Tarun Plus category only to qualifying borrowers who have successfully repaid a previous Tarun-category Mudra loan.
PMMY is a repayable business loan scheme, not a government cash grant or a guarantee of loan approval.
PM Mudra Loan Categories and Limits
PMMY offers four loan categories based on the business's funding needs.
1. Shishu Loan: Up to ₹50,000
Shishu covers loans of up to ₹50,000. It may suit eligible micro-businesses that need relatively small amounts for starting operations, buying supplies or meeting initial working-capital requirements.
2. Kishor Loan: Above ₹50,000 to ₹5 Lakh
Kishor loans are available for amounts above ₹50,000 and up to ₹5 lakh. Eligible applicants may use the funding to expand operations, buy equipment or meet other qualifying business expenses.
3. Tarun Loan: Above ₹5 Lakh to ₹10 Lakh
Tarun covers business loans above ₹5 lakh and up to ₹10 lakh. Lenders assess the proposed business activity, repayment capacity, credit information and other relevant requirements before making a lending decision.
4. Tarun Plus Loan: Above ₹10 Lakh to ₹20 Lakh
Tarun Plus became effective on 24 October 2024. It is intended for entrepreneurs who previously obtained a Mudra loan under the Tarun category and successfully repaid it.
Eligible borrowers can seek loans above ₹10 lakh and up to ₹20 lakh under this category, subject to lender assessment and scheme requirements.
Important: Tarun Plus is not a general first-time loan category. Having a business plan alone does not satisfy its previous-Tarun-loan repayment condition.
Key Benefits of Pradhan Mantri Mudra Yojana
- Access to formal business financing for eligible micro-enterprises.
- Four loan categories, with a maximum limit of ₹20 lakh for qualifying Tarun Plus borrowers.
- Collateral-free lending under the scheme's applicable conditions.
- Support for qualifying term-loan and working-capital requirements.
- Financing for manufacturing, trading, services and eligible agriculture-allied activities.
- Loan availability through participating banks, NBFCs and microfinance institutions.
These features do not mean that every applicant receives a loan. Lenders evaluate applications and can decline them if the required conditions are not met.
PM Mudra Yojana Eligibility Criteria
PMMY primarily supports eligible borrowers engaged in, or planning, small income-generating business activities.
The following factors are relevant:
- The applicant should have an eligible small-business activity or a viable business proposal.
- The proposed activity should fall within the scheme's supported sectors.
- The applicant must satisfy the lender's applicable KYC, age, credit and repayment-capacity requirements.
- The requested loan should match a valid Mudra category and genuine business funding needs.
- Applicants for Tarun Plus must satisfy the successful repayment condition for a previous Tarun loan.
Individual lenders may require borrowers to be at least 18 years old. Applicants should check the specific lender's requirements rather than assuming that one checklist applies identically to every financial institution.
Which Businesses Can Apply for Mudra Loans?
Mudra financing may support a range of qualifying micro-enterprise activities, including:
- Small retail shops and trading businesses.
- Tailoring, garment production and repair businesses.
- Beauty salons, personal services and similar enterprises.
- Food processing and small food-service businesses.
- Eligible dairy, poultry and beekeeping activities.
- Purchase of business machinery, tools and equipment.
- Working capital for qualifying manufacturing and service activities.
Coverage depends on the purpose of the loan and the participating lender's policies. Traditional crop cultivation loans and personal consumption loans should not automatically be treated as Mudra business loans.
What Is the Interest Rate on a PM Mudra Loan?
PMMY does not have one fixed interest rate that applies to every bank and every borrower.
The actual rate can depend on the lender's policies, applicable regulatory requirements, loan amount, borrower profile and credit assessment.
Before accepting a loan, review the annual interest rate, processing charges, total borrowing cost, EMI amount, repayment period and any charges for missed payments.
Mudra loans should not be advertised or understood as interest-free government money. Borrowers must repay the principal and the applicable loan charges according to the agreement.
Documents Required for a Mudra Loan
Document requirements vary by lender, loan amount and business type. Commonly requested information may include:
- Aadhaar, PAN or other accepted identity documents.
- Address proof and applicable KYC details.
- Photographs, where required.
- Bank account details or statements.
- A description of the existing or proposed business.
- A business plan explaining how the funds will be used and repaid.
- Equipment quotations or purchase estimates, where relevant.
- Business registration, financial records or tax details, where applicable.
- Evidence of successful repayment of an earlier Tarun loan for Tarun Plus applications.
A newly established small business may have different documentation requirements from an existing enterprise seeking a larger loan. Follow the current checklist given by the lender.
How to Apply for a PM Mudra Loan
Applications can be made through participating lending institutions and their authorised channels. The Government's Jan Samarth portal also provides digital application services for supported credit-linked schemes.
- Estimate how much funding your business needs.
- Identify the relevant Shishu, Kishor, Tarun or Tarun Plus category.
- Review the official PMMY scheme information.
- Contact a participating bank or lender, or check the relevant facilities available on Jan Samarth.
- Ask for the interest rate, fees, repayment terms and required documents.
- Complete the lender's application and verification process.
- Submit business and identity documents as required.
- Save the application or acknowledgement reference.
- If approved, read the loan agreement carefully before accepting the funds.
Submitting a form is not the same as receiving loan approval. Final approval, loan amount and terms are decided by the lending institution.
How to Check Your Mudra Loan Application Status
Applicants who used a bank branch should contact that bank or use its authorised tracking service. Those who applied through an official digital platform can check whether the platform provides application tracking.
Keep your application reference number and registered contact details available. Do not disclose OTPs, online banking passwords or confidential financial information to unknown callers.
Is Mudra Yojana a Loan or a Subsidy?
PMMY is a business credit scheme. It is not a universal subsidy programme that provides money without repayment.
Borrowers must repay their loans in accordance with the lending agreement. A separate government programme may sometimes offer a different form of assistance, but that does not make every Mudra loan subsidised or free.
Be cautious of websites or agents promising instant approval, guaranteed funding or loan waivers in exchange for upfront payments.
Common Mudra Loan Application Mistakes
- Applying under an unsuitable loan category.
- Assuming Tarun Plus is open to all first-time borrowers.
- Submitting an unclear or unrealistic business proposal.
- Providing inconsistent identity or business information.
- Ignoring the total interest and repayment cost.
- Believing that collateral-free means no credit assessment.
- Paying unauthorised agents who promise guaranteed approval.
- Sharing banking passwords or OTPs on suspicious websites.
Frequently Asked Questions About PM Mudra Yojana
1. What is the maximum PM Mudra loan amount?
The maximum limit is ₹20 lakh for qualifying Tarun Plus borrowers. Standard Tarun loans cover amounts above ₹5 lakh and up to ₹10 lakh.
2. Can a first-time borrower get a ₹20 lakh Mudra loan?
Tarun Plus requires successful repayment of a previous Tarun-category Mudra loan. A first-time borrower does not meet that specific condition.
3. Are Mudra loans collateral-free?
PMMY provides collateral-free institutional credit, subject to the scheme's requirements. The lender can still assess creditworthiness, business viability and repayment capacity.
4. What is the Mudra loan interest rate?
There is no single fixed national rate for every borrower. The lender determines the applicable interest rate and other charges under its policies.
5. Is a Mudra loan free money from the Government?
No. A Mudra loan is repayable business financing and should not be confused with a cash grant.
6. Can women entrepreneurs apply for PMMY?
Yes. Eligible women entrepreneurs can apply through participating lenders, subject to the normal loan assessment process.
7. Can agriculture-related businesses receive Mudra financing?
Certain allied activities, including dairy, poultry and beekeeping, may qualify. Regular crop loans should not automatically be treated as Mudra loans.
8. Can an existing business apply for a Mudra loan?
Yes. Eligible existing micro-enterprises may seek financing for expansion, equipment or working capital, subject to lender approval.
9. Where can I apply for a Mudra loan online?
Check the authorised application services of participating banks or the eligible schemes available through the official Jan Samarth portal.
10. Does applying guarantee approval?
No. Approval depends on the lender's assessment of eligibility, documents, business requirements and repayment capacity.
Official PM Mudra Yojana Websites and Resources
- Department of Financial Services: Official PMMY Scheme Information
- Jan Samarth: Government Credit-Linked Schemes Portal
- Ministry of Finance Announcement: Tarun Plus and ₹20 Lakh Loan Limit
Disclaimer: e-Sarkari Yojna is an independent informational website. It is not a Government of India loan application portal or a lending institution. Actual eligibility, interest rates, fees, approval and repayment terms depend on the authorised lender. Verify the latest conditions through official sources before applying or sharing financial information.
Always check the official website for final and accurate information.
Visit official website: www.mudra.org.in ↗Last updated: 17 Oct 2026