
Atal Pension Yojana (APY)
Atal Pension Yojana offers a guaranteed minimum monthly pension of ₹1,000–₹5,000 from age 60.
Eligibility: Eligible Indian citizens aged 18 to below 40 who meet the income-taxpayer rules.
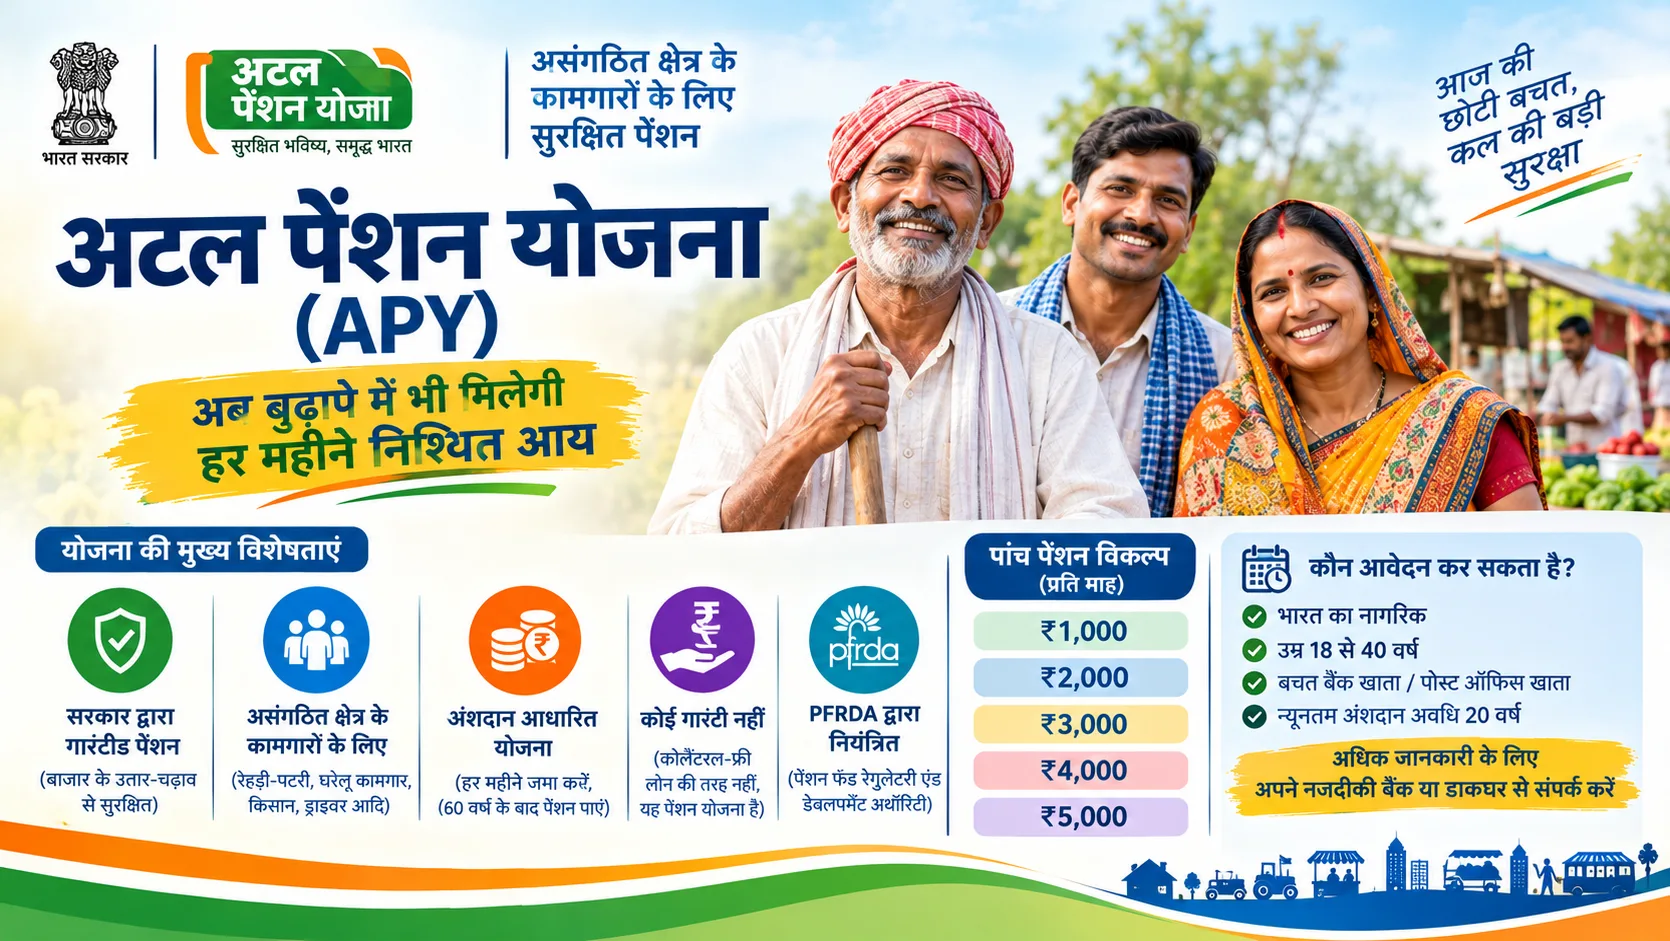
What Is Atal Pension Yojana (APY)?
Atal Pension Yojana (APY) is a government-backed, contribution-based pension scheme in India. Launched in May 2015 and effective from June 2015, it was introduced to help people, especially workers in the unorganised sector, build a source of income for retirement.
Under APY, an eligible subscriber makes regular contributions through a bank or post office savings account. After reaching the age of 60, the subscriber receives a government-guaranteed minimum monthly pension ranging from ₹1,000 to ₹5,000, depending on the chosen pension option and prescribed contributions.
The scheme is administered by the Pension Fund Regulatory and Development Authority (PFRDA) within the National Pension System framework.
APY is not a free monthly pension programme. Subscribers must contribute regularly according to the applicable pension plan.
How Much Pension Can You Receive Under APY?
Atal Pension Yojana offers five guaranteed minimum monthly pension options:
- ₹1,000 per month.
- ₹2,000 per month.
- ₹3,000 per month.
- ₹4,000 per month.
- ₹5,000 per month.
The pension starts at the age of 60 after the subscriber has satisfied the contribution requirements. The Central Government guarantees the selected minimum pension according to the scheme rules.
The actual pension option and required contribution are determined at enrolment. Not every subscriber automatically receives ₹5,000 per month.
Atal Pension Yojana Contribution Chart
The contribution required under APY depends primarily on two factors: the subscriber's age at enrolment and the chosen guaranteed minimum pension amount.
A younger subscriber generally makes smaller periodic contributions because the contribution period is longer.
The following examples are from the standard official monthly contribution chart for someone joining at age 18:
| Monthly pension from age 60Monthly contribution at joining age 18 | |
| ₹1,000 | ₹42 |
| ₹2,000 | ₹84 |
| ₹3,000 | ₹126 |
| ₹4,000 | ₹168 |
| ₹5,000 | ₹210 |
These figures apply to the example joining age of 18. The required contribution increases for people who join later.
For reference, the official contribution schedule includes monthly amounts of ₹291 for a ₹1,000 pension and ₹1,454 for a ₹5,000 pension at the age-40 contribution point. However, fresh enrolment must take place before the applicant completes 40 years of age.
Use the current official PFRDA APY resources or your participating bank's contribution chart for the exact amount applicable to your age.
Atal Pension Yojana Eligibility Criteria
Applicants must meet the following key requirements to open a new APY account:
- Be an Indian citizen.
- Be at least 18 years old and below 40 years of age when enrolling.
- Have a savings account with a participating bank or post office.
- Meet the applicable income-taxpayer eligibility restriction introduced in October 2022.
- Authorise contributions from the relevant savings account.
APY is particularly intended to improve retirement security for people in the unorganised sector. However, qualifying citizenship, age, income-taxpayer and other requirements are the main eligibility factors.
Can Income-Tax Payers Join Atal Pension Yojana?
From 1 October 2022, an Indian citizen who is or has been an income-tax payer cannot open a new APY account.
Subscribers who joined APY on or before 30 September 2022 can continue their existing accounts under the applicable rules, irrespective of their subsequent income-taxpayer status.
The term income-tax payer has a specific meaning under the relevant income-tax laws and APY notifications. Merely having a PAN or filing a return does not explain every eligibility scenario.
If your income-tax status is uncertain, confirm the position with the authorised bank or PFRDA before enrolling.
Key Benefits of Atal Pension Yojana
1. Guaranteed Minimum Pension from Age 60
A subscriber who fulfils the contribution requirements receives the selected government-guaranteed minimum pension after reaching the age of 60.
2. Pension for the Spouse
After the subscriber dies, the eligible spouse is entitled to receive the same guaranteed minimum monthly pension for life, according to the scheme rules.
3. Pension Wealth for the Nominee
After the death of both the subscriber and the spouse, the accumulated pension wealth specified under the scheme becomes payable to the nominee.
4. Government Minimum Pension Guarantee
The scheme provides a Central Government guarantee for the defined minimum pension. The treatment of investment performance follows the relevant APY rules.
5. Periodic Contributions Through a Savings Account
Contributions are collected through a participating bank or post office savings account using the agreed auto-debit arrangement.
How to Apply for Atal Pension Yojana
Eligible individuals can open an APY account through their participating bank or post office. Some authorised institutions also support digital enrolment.
- Contact the bank or post office where you hold a savings account.
- Ask for the current APY enrolment form or authorised online facility.
- Choose the guaranteed minimum pension amount you want to receive from age 60.
- Check the corresponding contribution amount for your age.
- Select the available monthly, quarterly or half-yearly contribution frequency.
- Provide the required identity, savings account, spouse and nominee details.
- Complete the applicable income-taxpayer and other eligibility declarations.
- Give consent for contribution auto-debit.
- Submit the application and keep the registration confirmation safely.
Opening an account requires successful verification of the applicable eligibility and enrolment details.
How to Register for APY Online
Some participating banks offer APY enrolment through their internet banking or mobile banking platforms. Authorised eAPY services may also be available to eligible applicants.
The exact online process depends on the bank and the services supported at the time of registration.
Use only official banking or PFRDA-authorised channels. Never share banking passwords, PINs or OTPs with an unauthorised agent.
How Often Do You Need to Contribute to APY?
Atal Pension Yojana supports three regular contribution frequencies:
- Monthly.
- Quarterly.
- Half-yearly.
The selected contribution amount is normally collected through the savings account using auto-debit instructions.
Subscribers must generally continue contributing from their enrolment age until they reach 60. The contribution period is therefore at least approximately 20 years.
Maintaining sufficient funds in the savings account helps prevent missed contributions.
Documents Required for Atal Pension Yojana
Exact documentation depends on the bank or post office's current KYC and enrolment requirements. Applicants should generally prepare:
- Participating bank or post office savings account details.
- Accepted identity and KYC information.
- Date of birth and age details.
- An active mobile number.
- Spouse and nominee information, where applicable.
- Income-taxpayer eligibility declaration.
- Consent for auto-debit and the selected pension amount.
Follow the institution's current document checklist rather than assuming every item is required in identical form at every bank.
What Happens If an APY Contribution Is Missed?
A contribution may fail when the savings account has insufficient funds or the auto-debit arrangement encounters another issue.
Delayed contributions can lead to recovery of pending amounts and applicable overdue charges or interest under the scheme rules.
If your contribution has not been debited:
- Check the available savings account balance.
- Contact your participating bank or post office.
- Ask whether any contributions remain pending.
- Confirm the applicable overdue amount and payment procedure.
- Review the account status after the issue is resolved.
The handling of overdue contributions and inactive accounts is governed by current PFRDA and banking procedures.
Can You Withdraw Money from APY Before Age 60?
APY is designed to provide retirement income from age 60, rather than to operate as an ordinary savings account with unrestricted withdrawals.
Voluntary exit before age 60 may be permitted subject to prescribed rules, adjustments and deductions.
Where historical government co-contributions apply, additional rules can affect the amount returned on early exit.
Before requesting closure, ask your bank or the authorised APY service to explain the current exit conditions and estimated amount payable.
What Happens If an APY Subscriber Dies?
After the subscriber reaches 60, the scheme provides for continuation of the guaranteed minimum pension to the eligible spouse following the subscriber's death.
After both the subscriber and spouse have died, the nominee becomes eligible for the specified pension wealth under the scheme rules.
If a subscriber dies before age 60, the surviving spouse may have options to continue the scheme or receive the amount payable under the applicable early-death provisions.
Families should contact the participating bank or PFRDA-authorised service to understand the documents and procedure relevant to their situation.
Atal Pension Yojana vs National Pension System (NPS)
Both APY and the National Pension System support retirement planning, but they have different benefit structures.
- Atal Pension Yojana: Offers defined government-guaranteed minimum pension options of ₹1,000 to ₹5,000 per month, with specific age and income-taxpayer eligibility restrictions.
- National Pension System: Uses a different investment-based retirement savings structure with its own contribution, withdrawal and annuity rules.
Applicants should compare the relevant eligibility, risk, contribution and retirement-income arrangements using official sources before choosing a pension product.
Frequently Asked Questions About Atal Pension Yojana
1. How much monthly pension is available under APY?
APY offers five guaranteed minimum monthly pension options: ₹1,000, ₹2,000, ₹3,000, ₹4,000 and ₹5,000, payable from age 60 subject to scheme conditions.
2. Can someone who has already turned 40 open a new APY account?
No. New enrolment must take place before the applicant completes 40 years of age. The eligible joining age starts at 18.
3. Can income-tax payers open an APY account?
From 1 October 2022, people who are or have been income-tax payers cannot open new APY accounts. Different continuity rules apply to eligible accounts opened before that date.
4. Does everyone receive ₹5,000 per month?
No. ₹5,000 is one available pension option. The subscriber must select that option and pay the corresponding prescribed contributions.
5. For how many years must APY contributions be paid?
Contributions are generally required from the time of enrolment until age 60, resulting in a contribution period of at least 20 years.
6. Can women join Atal Pension Yojana?
Yes. Eligible Indian women can join APY if they satisfy the applicable age, banking and income-taxpayer requirements.
7. Can government employees subscribe to APY?
Employment status alone does not automatically exclude every applicant. A person must satisfy all current eligibility rules, including the income-taxpayer restriction.
8. Does the spouse receive a pension after the subscriber dies?
Yes. The eligible spouse receives the same guaranteed minimum pension under the scheme's applicable survivor-benefit provisions.
9. Can an APY account be opened online?
Some authorised banks and digital services support online enrolment. Availability and verification procedures differ by institution.
10. Can one person open multiple APY accounts?
No. The scheme permits only one APY account per subscriber.
11. Will existing APY pensions stop after 2031?
The Government approved continuation of APY and related funding support through financial year 2030–31. That announcement does not mean existing pension entitlements automatically end in 2031.
Official Atal Pension Yojana Websites and Resources
- PFRDA APY Scheme: Official APY Information
- Department of Financial Services: Atal Pension Yojana Details
- India Post: APY Post Office Services
- Government Continuation Announcement: APY Extension Through FY 2030–31
Disclaimer: e-Sarkari Yojna is an independent informational website and is not operated by the Government of India, PFRDA or a participating bank. Eligibility, contribution amounts and exit procedures are subject to official rules. Verify all final details with PFRDA and your authorised bank or post office before enrolling. Never share banking passwords, PINs or OTPs with unauthorised persons.
Always check the official website for final and accurate information.
Visit official website: financialservices.gov.in ↗Last updated: 17 Oct 2026